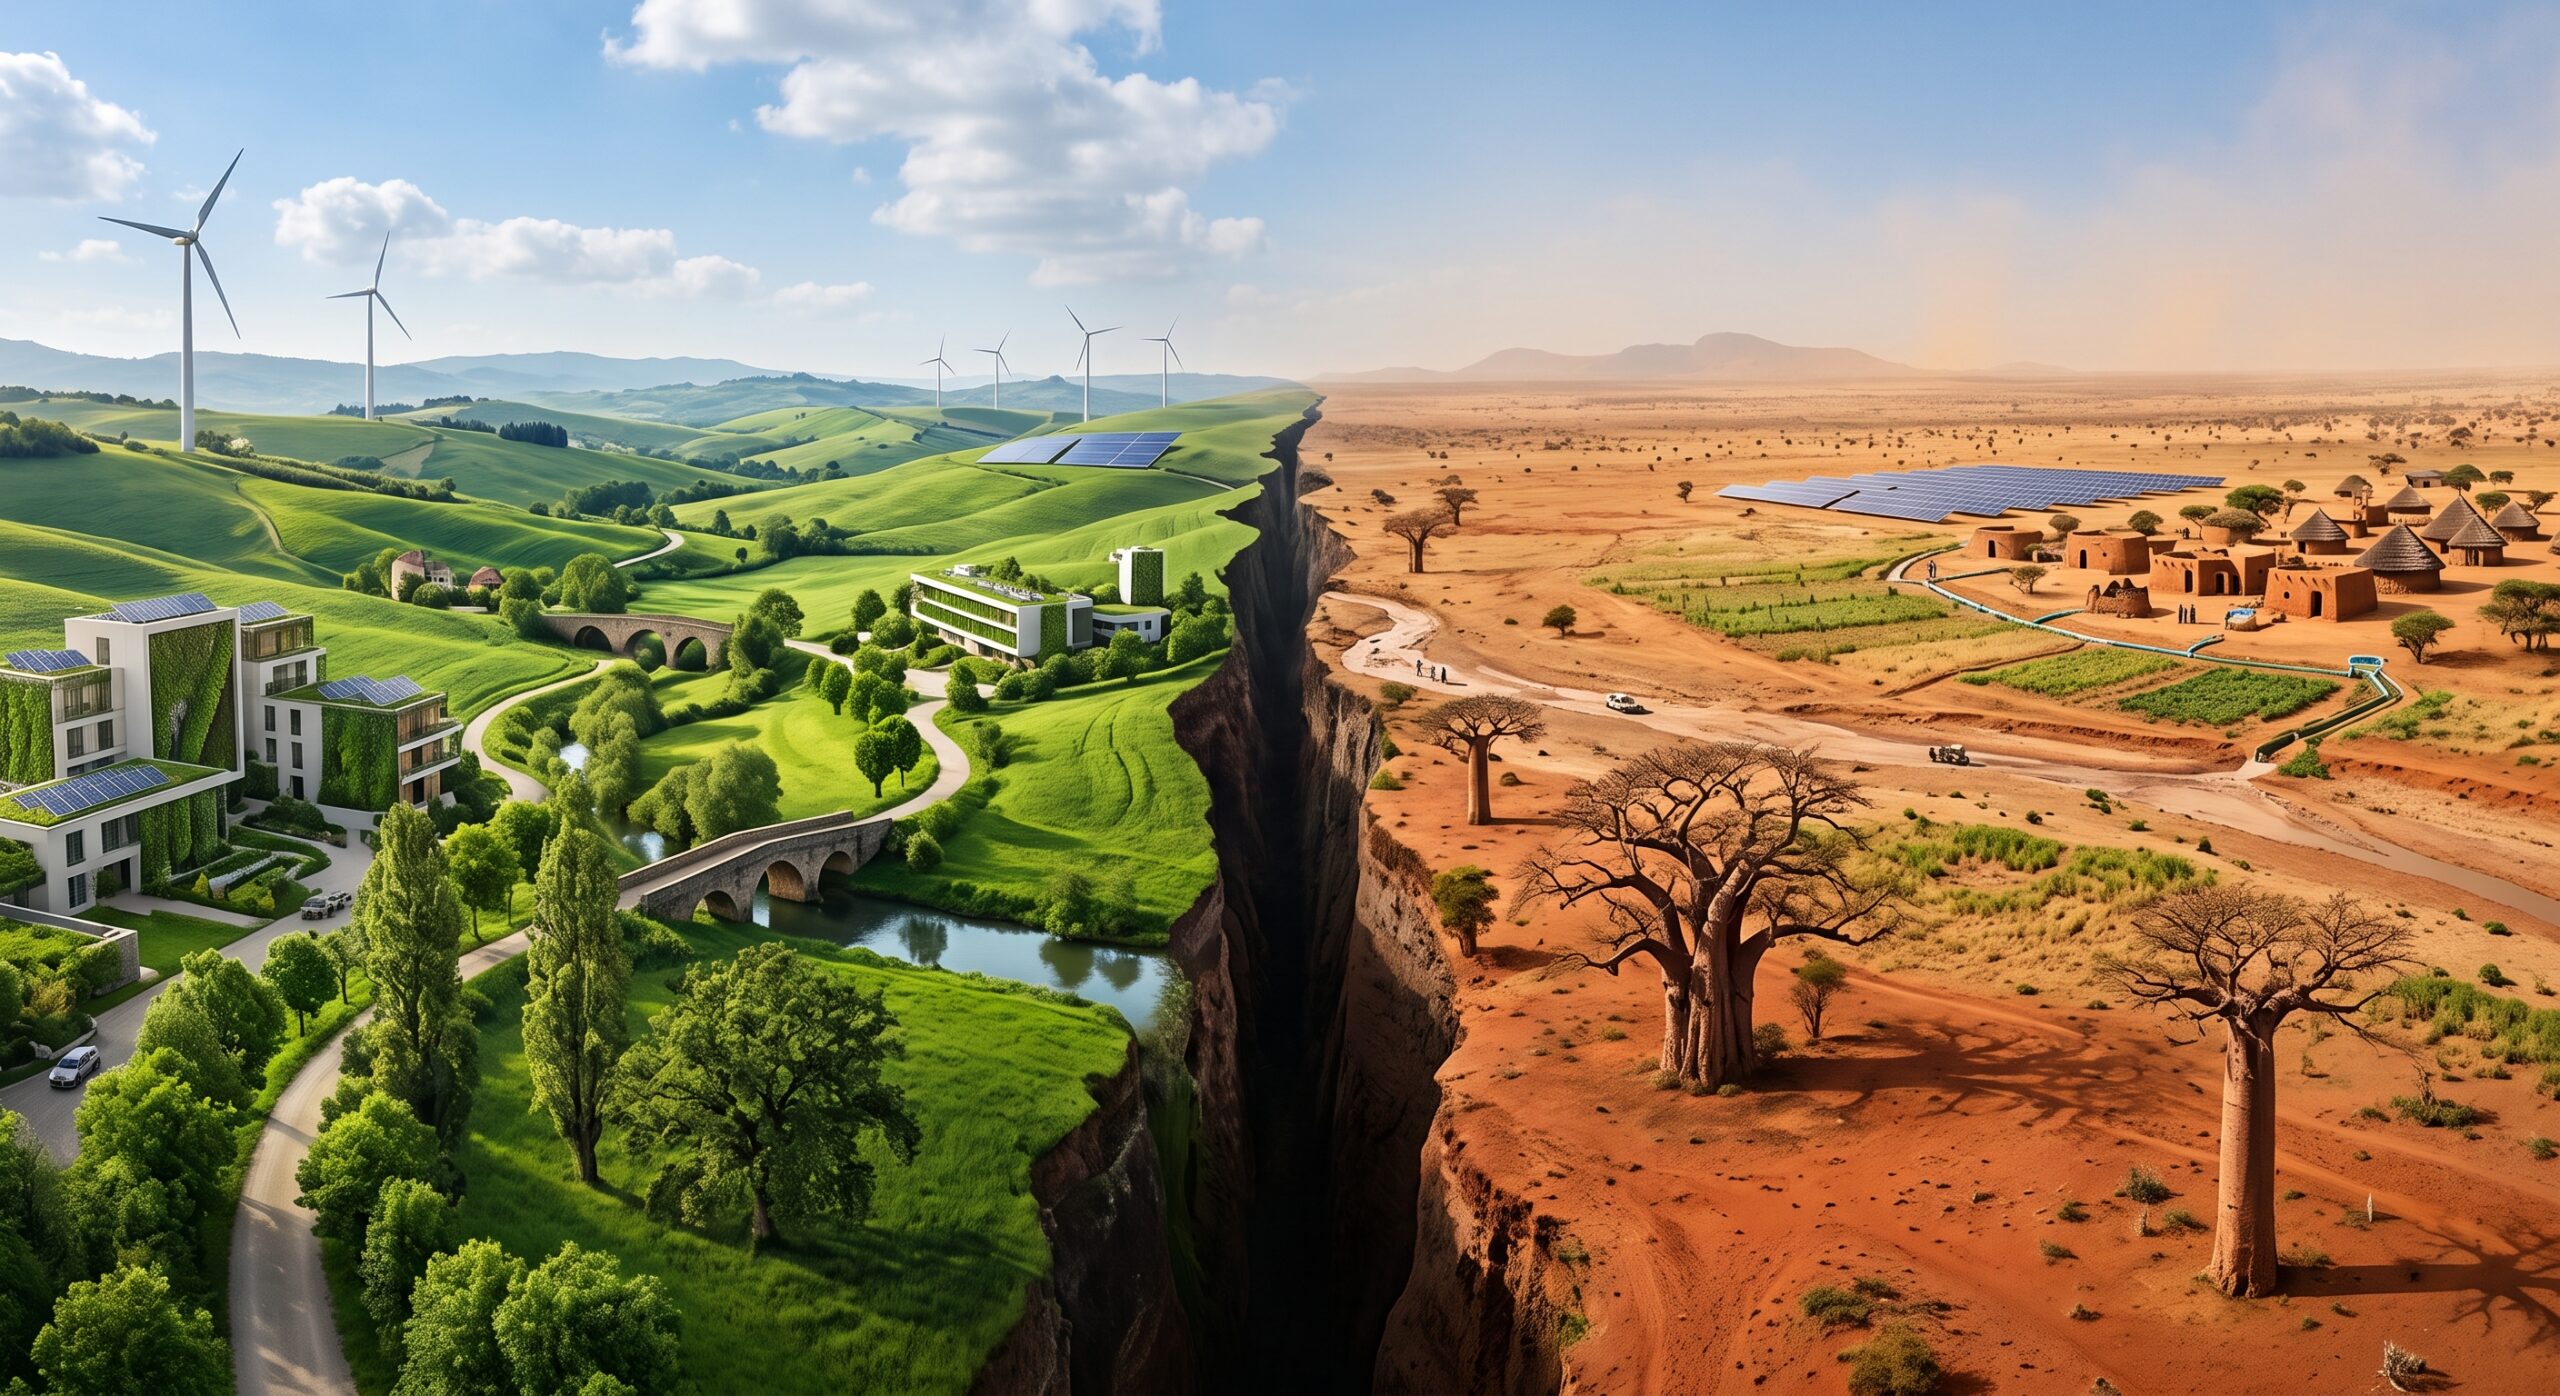
Two things are happening at once in sustainable finance, and they point in opposite directions.
In Europe, ESG fund flows have slowed and the regulatory framework is in a consolidation phase. Asset managers spent the past three years building reporting machinery for SFDR, then watched the rules around fund naming, disclosure categories and corporate sustainability reporting be reviewed, simplified and rescoped. Product teams have reclassified funds. Compliance teams have rebuilt templates. A good share of the work has gone into interpreting requirements rather than into investment decisions.
In Africa, the movement is the opposite. Development finance institutions, sovereign and bilateral agencies, and the blended finance vehicles they anchor are increasing commitments to energy, transport, water and digital infrastructure. Capital is being deployed into projects, into local funds, into private debt and into unlisted companies, often in markets where there is no ESG data vendor coverage at all.
These are not two separate stories. They are the same portfolio, seen from two ends.
The European investor is on both sides of the gap
A European institutional investor with an allocation to African infrastructure or to emerging market private assets is subject to the full European reporting apparatus on that allocation. Sustainability reporting obligations and the corporate due diligence framework push the requirement down the value chain: not only what the investor holds, but what sits underneath it, and what sits underneath that.
In practice, this means the same data points have to be produced for an African hydro project held through a local fund, itself held through a fund of funds, as for a listed European issuer covered by three data vendors. Principal adverse impact indicators, taxonomy alignment, greenhouse gas intensity, workforce and governance metrics: the reporting format does not care how hard the data was to obtain.
That is where the divergence becomes operational. The rules are harmonised. The data underneath them is not.
Why emerging market and unlisted data breaks the standard process
Four problems come up again and again, and they compound.
No coverage. Commercial ESG data providers cover listed issuers well and unlisted ones poorly. For a mid-sized African operating company held through a private fund, there is usually no rating, no reported scope 1 and 2 figures, and no structured filing to parse.
No common format. What does exist arrives as a GP quarterly report, an Excel annex, an impact appendix in a PDF, or a bespoke questionnaire built by a development finance institution around its own impact framework. Methodologies differ, perimeters differ, reference periods differ.
No identifier. Unlisted holdings rarely carry a clean identifier. Without one, the same company appearing in two different funds cannot be reliably matched, and exposure is either double counted or lost.
No timing alignment. Private vehicles report quarterly, often with a lag of sixty to ninety days. Listed portfolios report daily. Consolidating the two into one dated ESG view requires explicit rules about what is being compared to what.
The usual response is manual. Someone rekeys figures into a spreadsheet, applies a proxy where data is missing, and produces a number. It works once. It does not survive an audit, and it does not scale to a second reporting cycle.
The requirement is a consolidated view, with the workings attached
The objective is not to produce an ESG figure. It is to produce one that can be explained.
Three capabilities make that possible.
Lookthrough down to the underlying holdings. Aggregating ESG indicators at the fund level, using figures supplied by each manager, means aggregating inconsistent methodologies. Lookthrough resolves the portfolio into its actual underlying positions first, then applies one methodology across all of them. The number changes. More importantly, it becomes comparable.
Normalisation and quality control at the point of collection. Heterogeneous source files have to be standardised, deduplicated, categorised and tested before they enter the consolidated dataset. An indicator that has been extracted but not checked is a wrong figure that looks right, which is more dangerous than a blank cell.
Traceability. Every consolidated indicator should be clickable back to the document it came from, including the page of the GP report or the line of the questionnaire. When a coverage rate is low, the report should say so and say where the gap is, rather than quietly filling it with an estimate.
Coverage will never reach 100 per cent on an emerging market private portfolio. That is acceptable, provided the estimated portion is identified, the methodology is documented, and the auditor can follow the chain.
How Quantilia approaches it
Quantilia consolidates multi-asset portfolios across listed and private holdings, applies automated lookthrough, and produces ESG analysis on the resulting dataset rather than on manager-supplied summaries.
The ESG module collects ratings and indicators at issuer level, aggregates them by fund, by mandate and at total portfolio level after lookthrough, and produces the required regulatory outputs, including PAI indicators and taxonomy metrics, in the expected format. Because the aggregation runs on a single methodology applied consistently, each consolidated score can be investigated down to its components.
The supporting numbers: 800 data providers connected, 550 automated quality controls run on incoming files, 12 countries covered, more than 250 billion dollars of assets monitored for over 60 institutional clients, and ISO 27001 certification. Clients typically report up to 70 per cent of time saved on their reporting cycles.
What this means for 2027 planning
European frameworks will keep converging towards fewer, clearer and better enforced requirements. Development finance in Africa will keep expanding into exactly the asset types those requirements are hardest to apply to. Investors positioned in both will feel the pressure at the junction, and the junction is data infrastructure.
The institutions that handle this well will not be the ones with the largest ESG teams. They will be the ones that solved data collection, lookthrough and validation once, then reused it for every framework that came afterwards.
Ready to see how your ESG reporting chain would hold up? Book a scope review with our team.