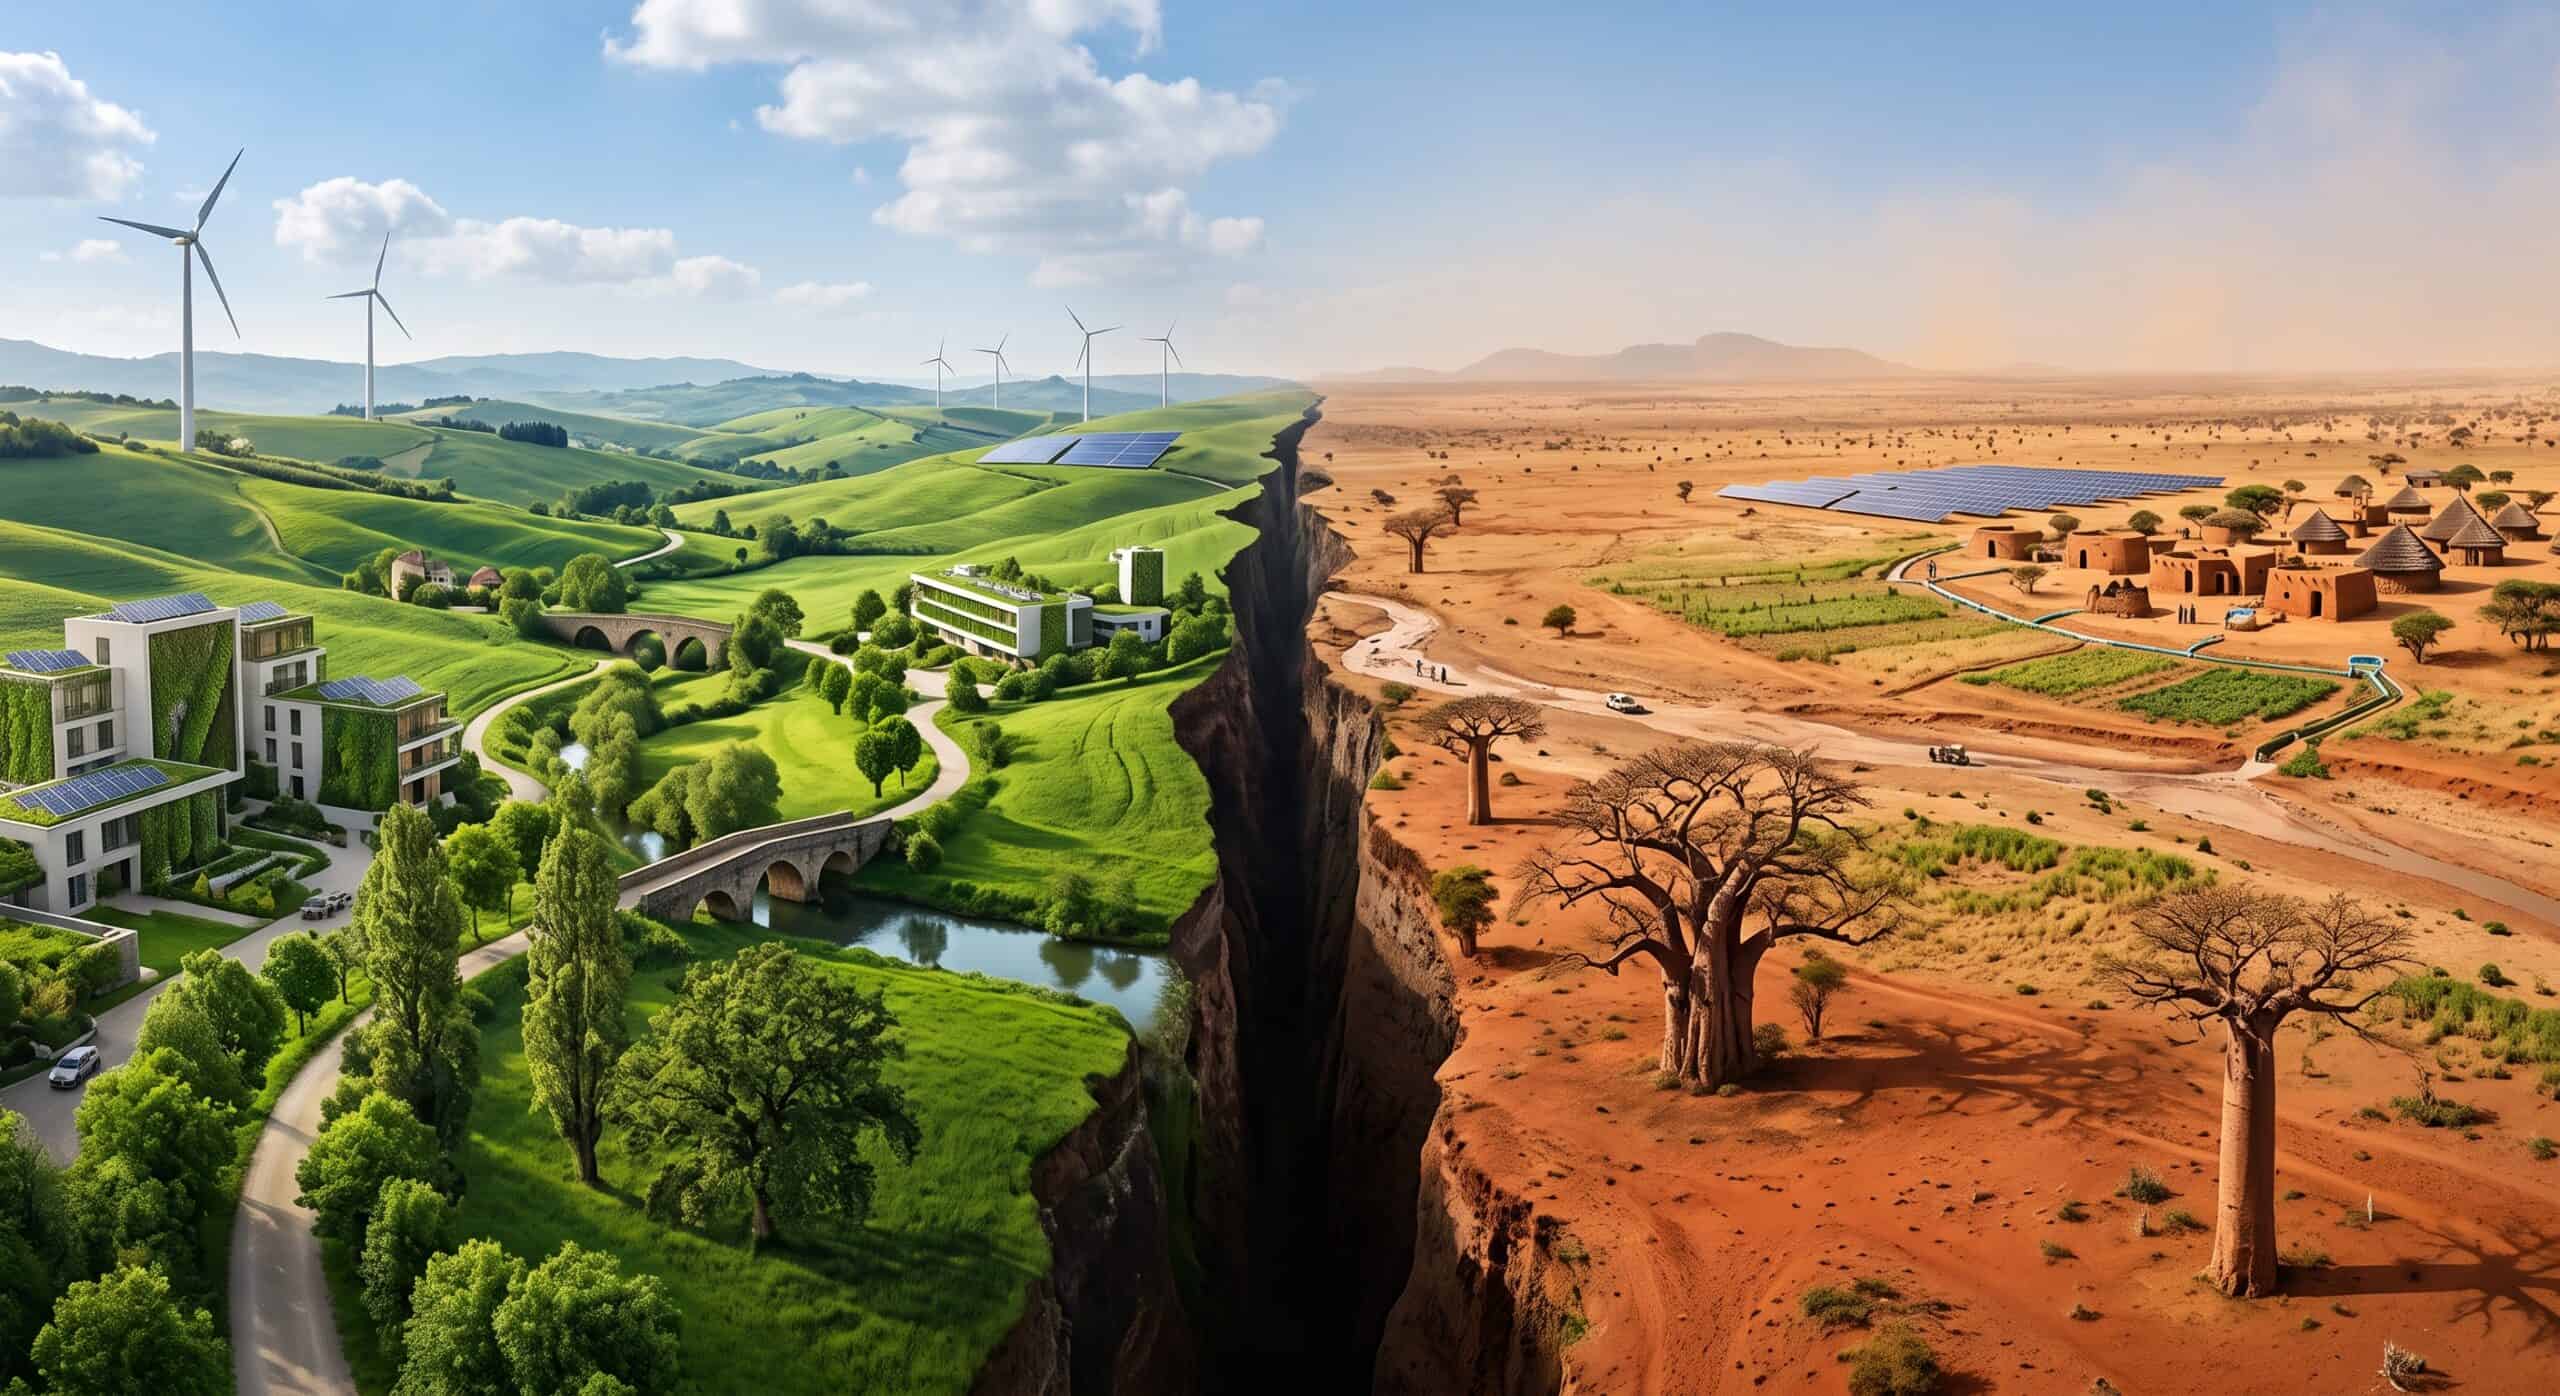
Two years ago, the direction of travel in sustainable finance looked settled. Europe wrote the rules, everyone else was expected to catch up, and the main question for institutional investors was how fast they could build the reporting machinery.
That assumption no longer holds.
The reversal, and its European echo
The change of administration in the United States in January 2025 turned ESG from a technical subject into a political one. Large American asset managers and banks left the net zero alliances they had joined a few years earlier. The federal climate disclosure rule stopped being defended. Several institutions dropped the terminology entirely from their reporting, while continuing to run much of the same analysis internally under different labels.
Europe did not follow that reversal, but it felt it. Global managers with US and European arms had little appetite for maintaining two opposite public positions. Political pressure inside the European Union to reduce the administrative burden on companies gathered momentum, and the simplification package moved to cut the number of companies in scope of corporate sustainability reporting and to push back application dates. Fund flows reflected the mood: sustainable fund launches slowed, product ranges were rationalised, and a number of funds were reclassified or renamed under tighter naming rules.
None of this removed the obligations. For the institutions still in scope, the reporting requirement, the due diligence duty across the value chain and the indicators to be produced are broadly unchanged. What changed is the enthusiasm around them. Compliance replaced conviction as the driver.
Africa kept going
The reversal did not travel south.
Development finance institutions, bilateral agencies and the blended finance vehicles they anchor increased their commitments through this period rather than reducing them. Energy, transport, water and digital infrastructure projects continued to reach financial close. The reason is structural: these institutions have sustainability mandates written into their founding texts, their capital is public or quasi public, and their investment case was never dependent on the popularity of a label in the Anglo-Saxon financial press.
More interesting is what happened on the regulatory side. While Europe was debating how much reporting to remove, several African jurisdictions were adding it. Nigeria set out one of the earliest national roadmaps for adopting the ISSB sustainability disclosure standards. South Africa, Kenya, Ghana and others have moved in the same direction, with regulators and exchanges issuing adoption guidance. In South Africa, amended pension regulation already obliges retirement funds to state how sustainability factors are considered in their investment policy, which puts the obligation at asset owner level rather than at issuer level.
The result is a genuine reversal of the usual assumption. On several points, an African institutional investor now operates under a clearer, more internationally aligned disclosure baseline than a European peer working through a framework in the middle of being rewritten. The markets that were expected to catch up are, in some respects, the ones setting the pace.
Why this matters practically for European investors
Because the exposure runs in the other direction.
A European pension fund, insurer or development agency with an allocation to African infrastructure or to emerging market private assets remains subject to the full European reporting apparatus on that allocation. The obligation pushes down the chain: not only what is held, but what sits underneath, and what sits underneath that.
So the same data points have to be produced for a hydro project held through a local fund, itself held through a fund of funds, as for a listed European issuer covered by three data vendors. Principal adverse impact indicators, taxonomy metrics, greenhouse gas intensity, workforce and governance data: the reporting template does not care how hard the data was to obtain.
The rules are harmonised. The data underneath them is not.
The four problems that compound
No coverage. Commercial data providers cover listed issuers well and unlisted ones poorly. For a mid-sized African operating company held through a private fund, there is often no rating, no reported scope 1 and 2 figures and no structured filing to parse.
No common format. What exists arrives as a GP quarterly report, an Excel annex, an impact appendix inside a PDF, or a bespoke questionnaire built by a development finance institution around its own framework. Methodologies, perimeters and reference periods all differ.
No identifier. Unlisted holdings rarely carry a clean identifier. Without one, the same company appearing in two funds is either double counted or lost.
No timing alignment. Private vehicles report quarterly, often with a lag of sixty to ninety days. Listed portfolios report daily. Consolidating the two into one dated view requires explicit rules about what is being compared with what.
The usual response is manual. Someone rekeys figures into a spreadsheet, applies a proxy where data is missing and produces a number. It works once. It does not survive an audit, and it does not scale to the next reporting cycle.
What a defensible answer looks like
The objective is not to produce an ESG figure. It is to produce one that can be explained.
Lookthrough down to the underlying holdings. Aggregating indicators at fund level, using figures supplied by each manager, means aggregating inconsistent methodologies. Lookthrough resolves the portfolio into its actual underlying positions first, then applies one methodology across all of them. The number changes, and it becomes comparable.
Normalisation and quality control at the point of collection. Source files have to be standardised, deduplicated, categorised and tested before entering the consolidated dataset. An indicator extracted but not checked is a wrong figure that looks right, which is more dangerous than a blank cell.
Traceability. Every consolidated indicator should lead back to the document it came from, down to the page of the GP report or the line of the questionnaire. Where coverage is low, the report should say so and say where the gap sits, rather than filling it quietly with an estimate.
Coverage will never reach 100 per cent on an emerging market private portfolio. That is acceptable, provided the estimated portion is identified, the methodology documented and the chain auditable.
How Quantilia approaches it
Quantilia consolidates multi-asset portfolios across listed and private holdings, applies automated lookthrough and runs ESG analysis on the resulting dataset rather than on manager-supplied summaries.
The ESG module collects indicators at issuer level, aggregates them by fund, by mandate and at total portfolio level after lookthrough, and produces the required regulatory outputs, including PAI indicators and taxonomy metrics, in the expected format. Because one methodology is applied consistently, each consolidated figure can be investigated down to its components.
The supporting numbers: 800 data providers connected, 550 automated quality controls run on incoming files, 8 countries covered, more than 250 billion dollars of assets monitored for over 60 institutional clients, and ISO 27001 certification. Clients report up to 70 per cent of time saved on their reporting cycles.
What to plan for
The political temperature around ESG will keep moving. The obligations attached to capital already committed will not move with it, and the assets where the data is hardest to collect are precisely the ones attracting new development finance.
The institutions that handle this well will not be the ones with the largest sustainability teams. They will be the ones that solved collection, lookthrough and validation once, then reused it for whichever framework arrives next.
Ready to test how your ESG reporting chain holds up? Book a scope review with our team.